
How the Appraisal Clause Works on a South Dakota Policy
What the appraisal clause says, what it covers, when to use it and the mistakes that cost policyholders money.
Independent claim appraisal · East River & West River
When the carrier accepts your claim but the check won’t cover the repair, South Dakota Insurance Appraiser builds an independent, line-item valuation and takes it through the appraisal process written into your policy.
Before you pick up the phone
Appraisal values covered losses. If the claim was denied outright, the first call is usually a South Dakota attorney, not South Dakota Insurance Appraiser.
Compare the carrier’s estimate with your contractor’s. A few hundred dollars can usually be closed with a supplement. Several thousand often justifies appraisal.
Policies carry deadlines for proof of loss, depreciation recovery and lawsuits. Know them before anything else happens.
Covered isn’t the same as paid
Most short claims aren’t denials. They’re estimates with missing slopes, unmatched siding, a basement scoped as one wall, or a pole barn priced like a garden shed. South Dakota Insurance Appraiser exists for that gap between “covered” and “paid in full.”
We value the loss from scratch, with our own inspection and measurements, never an edited copy of the carrier’s estimate. And we price it for where the property actually is: Sioux Falls labor, Black Hills access and a ranch two hours from the nearest supplier are not the same.
Twelve services
From one estimate review to full panel representation, every service is built around a valuation of your loss that can stand up to scrutiny. Hurricanes don’t reach the northern plains, but derecho winds, record hail, blizzards and Black Hills wildfire do.
 01
Named as your appraiser once you or the carrier demand appraisal under the policy.
 02
Houses, townhomes and condo units where the carrier’s estimate leaves real repair costs out.
 03
Retail, office, multifamily, church, school and association properties with large, layered losses.
 04
Shingle, metal, siding and gutter claims after South Dakota hail, from pea-size to record-size stones.
 05
Straight-line wind, derecho and tornado losses to roofs, siding, trees and structures.
 06
Burst pipes, appliance leaks, sewer backup endorsements and wind-driven rain inside the home.
 07
Structure fires, smoke and soot migration, and the contents inventory that follows.
 08
Ember, smoke, ash and heat damage from fires in the Black Hills and western prairie.
 09
Ice storms, ice dams, snow-load collapse and blizzard damage to roofs and structures.
 10
Machine sheds, pole barns, shops, grain bins and livestock buildings on farm and ranch policies.
 11
A line-by-line review of the carrier’s estimate before you decide on appraisal or a supplement.
 12
Neutral umpire work on appraisal panels where we represent neither side.
Quick gap check
Type in the two numbers you already have. If the difference is large, a conversation with South Dakota Insurance Appraiser makes sense. If it’s small, a documented supplement may close it faster and for less.
The full appraisal payoff estimator adds appraiser and umpire fees and shows your break-even point.
The process
The appraisal clause turns an open-ended argument into a defined process with a binding result. Here’s the path from first call to signed award.
We read the policy, the carrier’s estimate and your photos, then tell you honestly whether appraisal fits.
We inspect, measure and build a line-item estimate priced for your part of South Dakota.
Appraisal is demanded in writing and South Dakota Insurance Appraiser is named as your appraiser.
We work through the estimate with the carrier’s appraiser. Most of the gap usually closes here.
Anything left goes to a neutral umpire. Two signatures set the amount of loss.
East River · West River
The Missouri River splits South Dakota in two, and the weather on each side shows up differently on a roof and in an estimate. South Dakota Insurance Appraiser works both sides of the river.
The most populated corner of the state, from Sioux Falls and Brookings down to Yankton and Vermillion. Hail and wind claims dominate, the 2019 Sioux Falls tornadoes and the 2022 derecho are still fresh, and the Big Sioux River and Missouri River bring flood questions to low ground.
Flat farmland, glacial lakes and long open stretches around Aberdeen, Watertown, Huron and Mitchell. Blizzards pack snow onto roofs, summer storms hammer steel buildings, and tornado history runs from Spencer to Delmont.
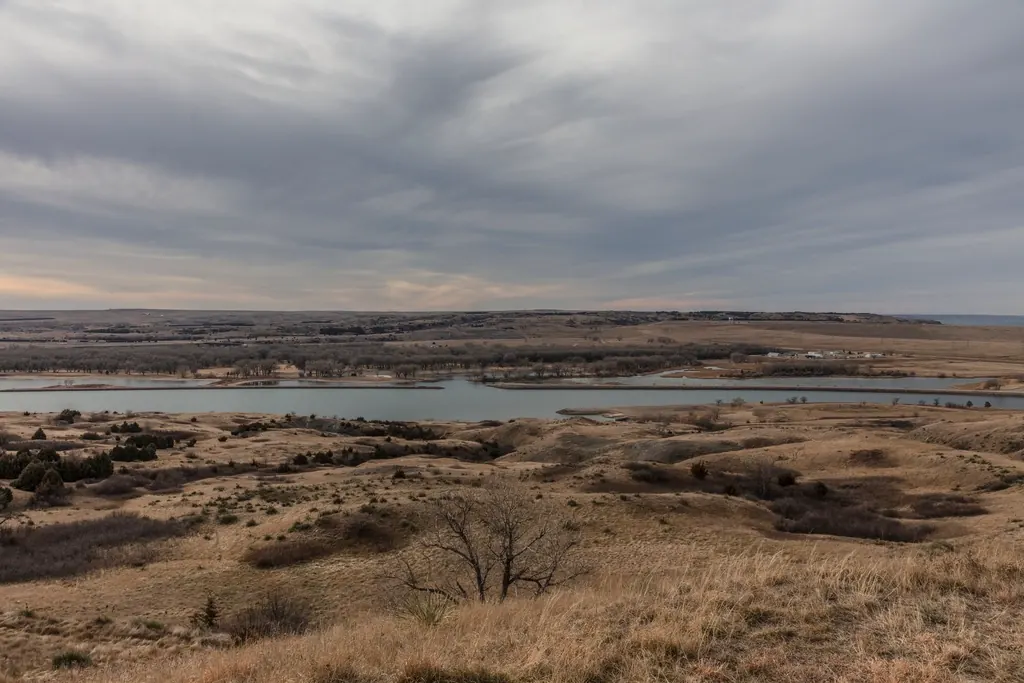
Pierre, Fort Pierre and the long Missouri River reservoirs, where East River meets West River. The country’s largest recorded hailstone fell near Vivian, and the 2011 river flood reached homes in the capital.
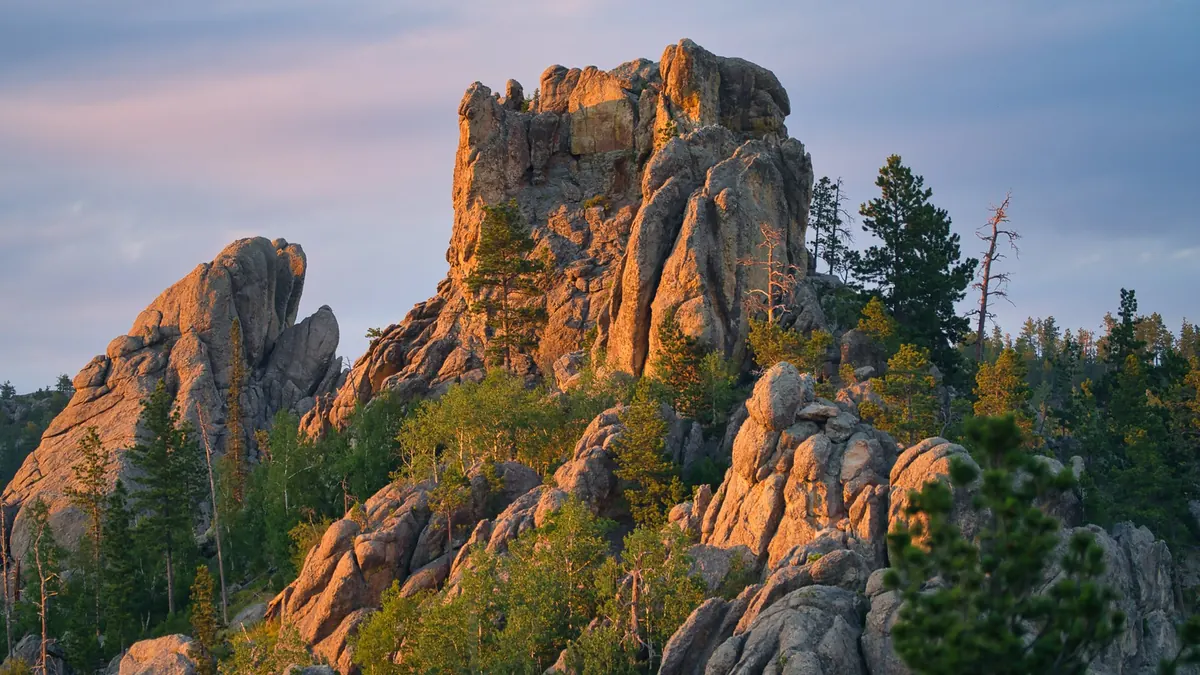
Rapid City, Spearfish, Sturgis and the ranch country beyond. Ponderosa forests bring wildfire risk, storms off the Hills drop big hail, and early blizzards like the 2013 storm can bury roofs in feet of wet snow.
Weather on the record
These events still shape how carriers and appraisers look at claims here. Each one taught South Dakota Insurance Appraiser something about how damage shows up, and where estimates fall short.
Overnight flooding on Rapid Creek reshaped the city and led to the greenway that runs through it today.
A violent tornado destroyed much of Spencer in McCook County, one of the deadliest in state history.
More than 80,000 acres burned in the southern Black Hills, a benchmark for wildfire risk in the region.
The largest hailstone recorded in the United States fell near Vivian in Lyman County.
Record releases flooded low ground from Pierre and Fort Pierre down through southeast South Dakota.
An early storm buried western South Dakota and the northern Hills in heavy, wet snow.
Three tornadoes touched down inside the state’s largest city in a single night.
Hurricane-force straight-line winds crossed eastern South Dakota, and a tornado struck Castlewood.
Extreme June rain pushed the Big Sioux River to historic levels in the state’s southeast corner.
Scroll or swipe sideways for more years →
Free & private
Run the numbers before you call. Every calculator works in your browser; nothing you type is stored or sent.
 ΔCalculator
Size the dispute, test where an award might land and subtract realistic fees to see your net.
 ACVCalculator
Estimate the first ACV check, the depreciation held back and the total after repairs.
 ◭Calculator
Turn a footprint and pitch into roof squares, order quantities and a rough replacement figure.
 %Calculator
Convert a wind/hail percentage deductible into dollars and compare it with a flat deductible.
 ◷Planner
Build a claim and appraisal timeline from your date of loss and export it to your calendar.
 A+Checklist
Answer twelve questions and get a letter grade plus a to-do list before you demand appraisal.
 ÷Calculator
See whether underinsurance could shrink a farm, commercial or HOA payment, and by how much.

Choosing help
Each professional solves a different problem. South Dakota Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.
Choose this when coverage is accepted and the number is the fight.
Choose this when you want help managing the whole claim from the start.
Choose this for denials, bad-faith concerns or a deadline that’s close.
FAQ
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser, we inspect, build our own line-item estimate, work with the carrier’s appraiser and, if needed, present open items to a neutral umpire.
No. A public adjuster manages and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage is accepted, you have the carrier’s estimate, and the gap between it and your contractor’s number is meaningful, usually more than about 10% or several thousand dollars.
On the amount of loss, generally yes, once two of the three panel members sign. That is why documentation matters before you demand appraisal.
Each side usually pays its own appraiser and half of the umpire. We put our fee in writing before work starts, and the first conversation is free.
Yes. We work in all 66 counties, from Sioux Falls and Aberdeen to Pierre, Rapid City and the ranches in between.
Articles
Practical guides from South Dakota Insurance Appraiser on policy language, documentation and strategy.
What the appraisal clause says, what it covers, when to use it and the mistakes that cost policyholders money.
A practical checklist for photographing and recording hail damage so the claim, and any appraisal, rests on solid evidence.
The May 2022 derecho showed how much damage straight-line wind can do. Here is how those claims work and where they go wrong.
Storm season is claim season
A short review now can keep you from accepting a settlement that won’t cover the repair.
Start with a conversation
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing.